Renters insurance comes with numerous benefits, but is it worth the cost?

Why you can trust Insurify: Comparing accurate insurance quotes should never put you at risk of spam. We earn an agent commission only if you buy a policy based on our quotes. Our editorial team follows a rigorous set of editorial standards and operates independently from our insurance partners. Learn more.
If you’re a renter, your landlord is responsible for insuring the building, whether it’s an apartment, condominium, house, or other dwelling. Your landlord’s insurance coverage doesn’t extend to your possessions, though. If you want protection for yourself and your belongings, you’ll need an HO-4 insurance policy.
An HO-4 policy is also known as renters insurance or tenant insurance. It’s an insurance policy specifically for renters. HO-4 policies protect your personal belongings from theft, fire, and other covered perils.
Having an HO-4 policy isn’t a legal requirement, but some landlords require you to carry one.
Why are HO-4 policies important?
Renting is traditionally viewed as a precursor to owning a home, but a 2023 survey of renters by Avail, a Realtor.com company, found that only 30% were looking to purchase a home in the next 12 months.[1] This is down from 34.6% in July 2022. One of the primary reasons for the delay among renters is concerns about inflation and rising interest rates.
If you prefer to rent, having proper renters insurance coverage is essential.
An HO-4 policy provides a wide-ranging protective net over your personal belongings in the event of covered hazards and incidents. Without it, you and your possessions could be left unprotected when disaster strikes. If there’s damage to the home or apartment, making it uninhabitable for a period, renters insurance can cover accommodations, meals, and other eligible expenses during that time.
Key benefits of an HO-4 policy
Having renters insurance not only protects you during covered events, but it can also provide peace of mind. Here are some of the key benefits of an HO-4 policy:
Protection for your belongings: An HO-4 policy covers the cost to repair or replace your possessions if they’re damaged, destroyed, or stolen.
Liability protection: Your policy protects you financially if someone is injured in your rental home or if you accidentally damage someone else’s property. This coverage can include protection for medical expenses and legal costs.
Loss of use: An HO-4 policy reimburses you for additional living expenses if you have to live somewhere else temporarily due to a covered peril.[2]
Peace of mind: Experiencing a disaster or other covered event is stressful enough without adding financial consequences. Knowing you’re covered through renters insurance can relieve some of that added stress.
Affordability: Renters insurance is typically very affordable, providing valuable coverage at a reasonable cost.
Components of an HO-4 policy
Most HO-4 policies include three types of insurance coverage:

Renters insurance covers the cost of repair or replacement of personal belongings that a covered peril damages or destroys. Your belongings are also protected against theft. Often, you can choose between replacement cost or actual cash value coverage when you insure your personal items.
Some insurers may offer additional protection through extra add-on coverages.
What is covered under an HO-4 policy?
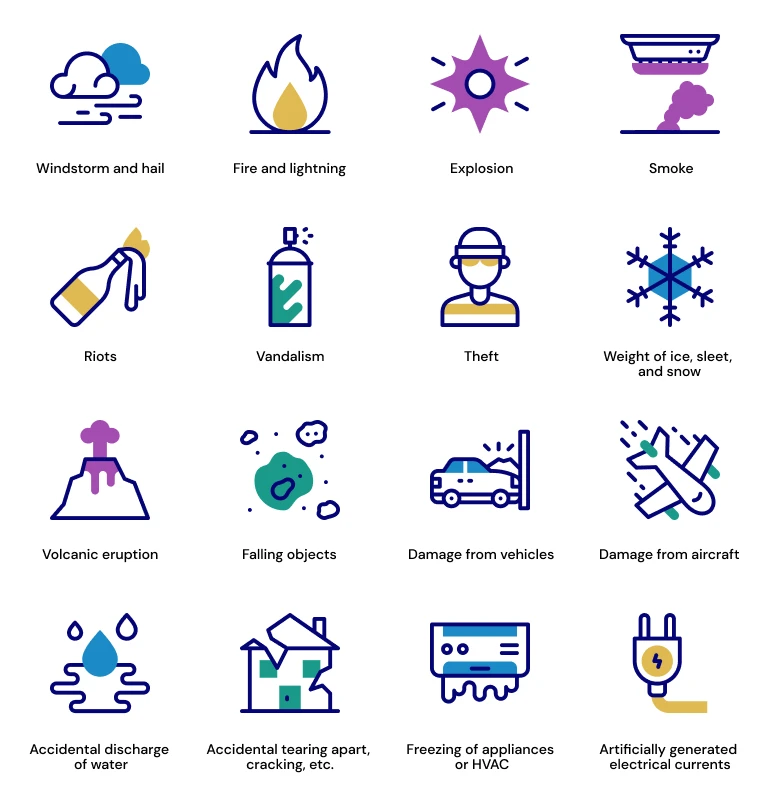
HO-4 insurance policies generally include coverage against the following perils:
What isn’t covered under an HO-4 policy?
As a renter, you’re protected for numerous common and not-so-common events and hazards.[3] Unfortunately, some perils typically aren’t covered under a standard HO-4 policy, including:
Expensive belongings that exceed your coverage limits
Structural damage to the rental property
Policy exceptions can vary between insurers. Contact your insurance agent to determine what is and isn’t included in your HO-4 policy.
How do you apply for an HO-4 policy?
If you’re interested in an HO-4 policy, start by getting quotes from several insurance companies that offer renters insurance. Compare rates and coverages to find the best fit for your needs.
Once you’ve found the coverage you want, apply for the policy. You can typically apply for insurance coverage online through the insurer’s website, but some offer in-person or phone assistance.
The insurance company may ask you to provide personal and property information when getting a quote or applying. This information could include:
Your full name
Date of birth
Rental property address
Number of people living in the rental property
Safety features and other property details
Follow the insurer’s instructions to apply for a renters insurance policy.
The average cost of an HO-4 policy
The average cost of an HO-4 policy is $173 annually, according to data from the National Association of Insurance Commissioners.[4] That’s roughly $14.42 per month.
Factors affecting the cost of an HO-4 policy
Where you live plays a role in how much you pay for renters insurance. For example, the average cost of an HO-4 policy in Georgia is $212 annually, while an HO-4 policy in Iowa is $136 on average.[4]
Other factors that affect HO-4 policy costs include:
The value of the belongings and assets you want to protect
Coverage types and limits
Deductibles
Claims history
The insurer you choose factors into the cost of your insurance policy. Renters insurance is usually cheaper than homeowners insurance, but it’s still a good idea to shop around to be sure you find the best rates.
How does an HO-4 differ from other policy options?
Other homeowners insurance policy types relate specifically to owners, not renters. If you don’t own the property where you reside, most other home insurance policy options don’t apply to you.
Another major difference between an HO-4 policy and other insurance policies is that renters insurance doesn’t include coverage for the rental property itself. This is the landlord’s responsibility.
An HO-6 policy, or condo insurance, also covers a single condo unit but is specifically for people who own the condo, not renters. Because condo insurance offers more protection, it typically costs more than renters insurance. If you rent a condo or other property, renters insurance is the best option.
HO-4 policy FAQs
If you’re looking for renters insurance, this additional information may help as you research your options.